
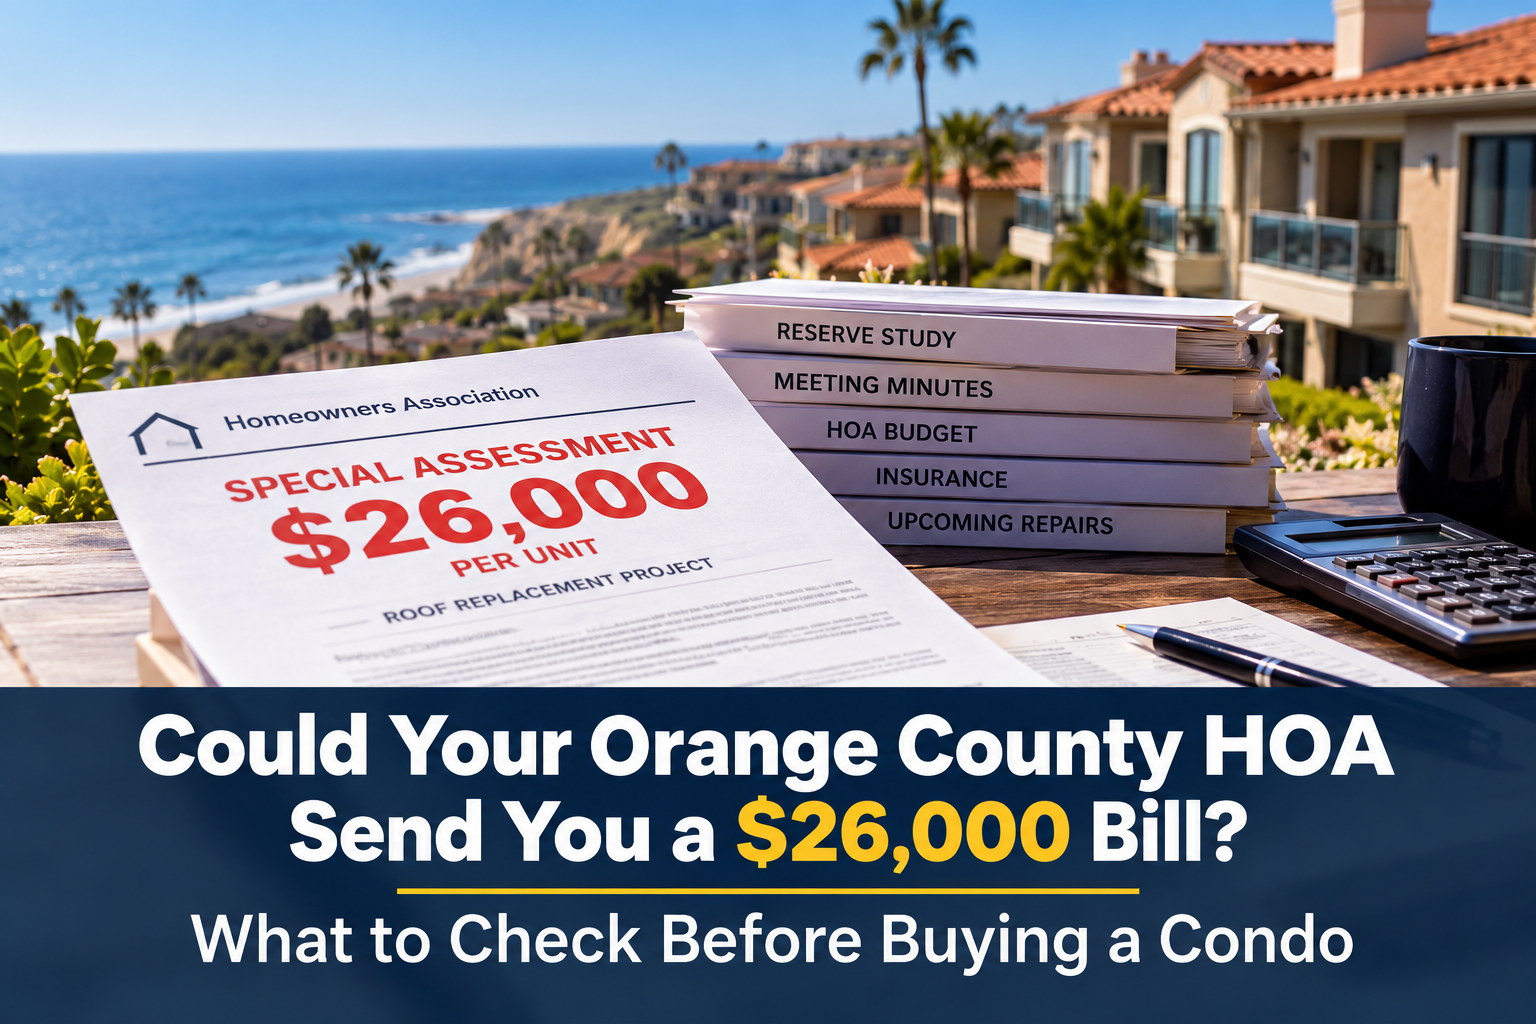
Imagine buying an Orange County condo, budgeting carefully for your mortgage, property taxes, insurance and monthly HOA dues — and then receiving a bill from the homeowners association for more than $26,000.
That is the situation some San Clemente homeowners say they are facing.
[ABC7 reported on September 1, 2026](https://abc7.com/article/san-clemente-hoa-emergency-assessment-roof-replacement/), that homeowners at a San Clemente condominium complex were challenging an emergency assessment of more than $26,000 per unit for roof replacements. Residents interviewed by ABC7 questioned whether the project qualified as an emergency and described the financial strain the assessment could create, particularly for retirees and homeowners on fixed incomes. The HOA board declined to comment because of ongoing legal matters, and the homeowners' allegations have not been established as legal findings.
The dispute will ultimately depend on facts specific to that association.
But for anyone thinking about buying a condo in San Clemente, Dana Point, Laguna Niguel, Laguna Hills, Lake Forest or elsewhere in Orange County, the story highlights something buyers sometimes overlook:
You are not only buying the condo. You are also buying into the financial condition of its HOA.
And that deserves just as much attention as the kitchen, the view and the monthly payment.
A Low HOA Fee Doesn't Tell You the Whole Story
Buyers naturally compare monthly HOA dues.
A condo with $350 monthly dues may initially look more attractive than one charging $550.
But the monthly number alone tells you very little about the financial health of the association.
The bigger questions are:
- How much money does the HOA have in reserves? • What major repairs are approaching? • Has the association been putting aside enough money for those repairs? • Has maintenance been postponed? • Are any special assessments already approved or being discussed? • Does the HOA have outstanding loans? • Are insurance costs rising? • Are there structural, roofing, plumbing, electrical or other major projects on the horizon?
An association can have relatively low monthly dues and still face expensive repairs later.
Conversely, somewhat higher dues may reflect an association that is consistently setting money aside for major future expenses.
That is why I would never evaluate a condo based solely on the HOA payment.
What California HOAs Are Supposed to Study
California law contains specific requirements regarding HOA reserve planning.
Under [California Civil Code Section 5550](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=5550.&lawCode=CIV), qualifying common-interest developments generally must conduct a reasonably competent visual inspection of major components the association is responsible for maintaining at least once every three years. The association must review the reserve study annually and consider necessary adjustments.
The study includes major components with remaining useful lives of less than 30 years, their estimated replacement or repair costs, and a reserve funding plan for those future expenses.
Think about what that could include in a condominium community:
Roofs. Plumbing. Exterior components. Elevators. Paving. Common-area structures. Electrical systems. Pools and other major shared improvements.
The important issue for a buyer isn't simply whether a reserve study exists.
It's what the reserve study says.
One Number I Want Buyers to Look At: Reserve Funding
California's reserve disclosures can provide an especially useful comparison.
[Civil Code Section 5565](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=5565.&lawCode=CIV) requires the association's reserve summary to disclose, among other things:
- The estimated amount of reserves needed • The amount actually accumulated • The percentage funded • The reserve deficiency expressed on a per-unit basis
That per-unit reserve deficiency can be an eye-opener.
Suppose an HOA's reserve study indicates it should have substantially more money accumulated for future projects than it actually has.
That doesn't automatically mean a special assessment is coming.
But it should make you ask more questions.
Where will the money come from when those repairs become necessary?
Possible answers include higher monthly assessments, borrowing by the association, delaying work — or a special assessment to homeowners.
Look for Repairs That Have Been Deferred
California's annual HOA budget disclosures can provide another important clue.
The [annual budget report](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=5300.&lawCode=CIV) must disclose whether the board has decided to defer or not undertake certain major repairs or replacements. It also must state whether the board anticipates that one or more special assessments may be required for major components or adequate reserves. The report also includes information about certain outstanding HOA loans and insurance coverage.
That means buyers should not stop at:
"Are there any special assessments right now?"
A much better question is:
"Are there major expenses coming that could result in a special assessment later?"
Those are two very different questions.
Read the HOA Meeting Minutes
This is one of my favorite sources of information when reviewing an HOA.
California law provides that, when requested by a prospective purchaser, the seller must provide approved HOA board meeting minutes — excluding executive-session meetings — from the [previous 12 months](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=4525.&lawCode=CIV).
Read them.
You're looking for recurring discussions involving things such as:
Roof leaks. Water intrusion. Plumbing failures. Insurance problems. Reserve shortages. Engineering reports. Contractor bids. Structural repairs. Litigation. Special assessments. HOA loans.
One mention doesn't necessarily mean there is a major problem.
But if the same expensive issue appears month after month without being resolved, I want my buyer to know about it before removing contingencies.
California Places Limits on Some Special Assessments — But There Are Exceptions
Under [California Civil Code Section 5605](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=5605.&lawCode=CIV), an HOA board generally cannot impose special assessments that, in the aggregate, exceed 5% of the association's budgeted gross expenses for that fiscal year without approval from a majority of a quorum of members.
There is, however, an important exception for qualifying emergencies.
[Civil Code Section 5610](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=5610.&lawCode=CIV) allows assessment increases necessary for certain emergency situations, including certain court-ordered expenses, hazardous conditions involving health or safety, and certain extraordinary expenses that could not reasonably have been foreseen when the annual budget was prepared. For the unforeseen-expense provision, the board must make written findings explaining why the expense was necessary and could not reasonably have been anticipated.
That distinction is part of the disagreement being reported in the San Clemente case. Homeowners quoted by ABC7 contend that the roofing work should be considered deferred maintenance rather than an unforeseen emergency; the board did not provide ABC7 with its position because of ongoing legal matters.
So the news report should not be read as a legal determination about who is right.
For buyers, though, the lesson is much simpler:
Find out what expensive work the HOA already knows may be coming.
HOA Problems Can Affect Your Mortgage Too
There is another reason I pay close attention to HOA finances: I'm looking at the property from both the real-estate and mortgage sides.
A condominium project itself may need to satisfy lender requirements — not just the individual borrower.
[Fannie Mae's current condominium guidelines](https://selling-guide.fanniemae.com/) allow lenders to review items including HOA meeting minutes, reserve studies, engineering reports, necessary repairs and special assessments when determining project eligibility. Projects with certain unaddressed critical repairs can be ineligible for Fannie Mae financing until the issues are resolved.
Under Fannie Mae's full-review standards, lenders also evaluate the HOA budget and replacement reserves.
So an HOA issue can become more than an unexpected homeowner expense.
In some circumstances, it can also affect financing, refinancing and the future pool of buyers for the property.
That's why I want these questions answered as early as possible.
For more on how California's new reserve funding law could affect HOA costs, see our article on [AB 2050 and HOA reserve requirements](/blog/ab-2050-hoa-reserve-requirements). For information on HOA master insurance and what condo buyers should know about coverage, see our article on [HOA master insurance and HO-6 policies](/blog/hoa-master-insurance-ho6-condo-orange-county).
My Condo Buyer HOA Checklist
Before buying an Orange County condo, I would want to review:
- 1. The most recent reserve study — including the percentage funded and projected major repairs. • 2. The current HOA budget and financial statements. • 3. The reserve deficiency per unit. • 4. At least 12 months of approved board meeting minutes. • 5. Current and recently completed special assessments. • 6. Special assessments that have been approved but aren't yet due. • 7. Major projects being discussed but not yet formally approved. • 8. Outstanding HOA loans. • 9. Master insurance coverage and deductibles. • 10. Any litigation, structural concerns, engineering reports or deferred maintenance. • 11. The age and expected remaining life of major components such as roofs, plumbing and other shared systems. • 12. Whether the project presents any financing concerns for the loan program you plan to use.
[California law](https://leginfo.legislature.ca.gov/faces/codes_displaySection.xhtml?sectionNum=4525.&lawCode=CIV) requires sellers of units in common-interest developments to provide prospective purchasers with numerous HOA documents and disclosures, including current regular and special assessments and approved assessment changes that have not yet become due.
Don't just collect those documents.
Read them.
A $26,000 Assessment Is a Reminder to Look Beyond the Monthly Payment
The San Clemente dispute is getting attention because $26,000 is a startling number.
But the broader lesson applies to condo buyers throughout Orange County.
When you buy into an HOA, part of your property's future financial risk is tied to decisions made collectively by the association.
No one can guarantee that an HOA will never levy a special assessment. Unexpected expenses really do happen.
But good due diligence can help identify warning signs before you buy.
A beautiful condo with affordable monthly dues may still be a great purchase.
I simply want my buyers to know what those dues are funding, what they're not funding, and what expenses could be waiting around the corner.
Because the best time to discover that an HOA may need millions of dollars for roofs, plumbing, structural repairs or another major project is before you own one of the units — not after the bill arrives.
Thinking about buying an Orange County condo? Fixed Rate Real Estate helps buyers look beyond the listing photos and monthly HOA payment. We can help you evaluate the property, HOA documentation and potential financing considerations before you commit. [Contact us](/contact) to get started.
This article is for general educational purposes and is not legal advice. HOA laws, governing documents and individual circumstances vary. Questions regarding an association's legal authority or a specific assessment should be reviewed with a qualified California attorney.
Source: [ABC7 Los Angeles, September 1, 2026](https://abc7.com).
Broker/Owner, Fixed Rate Real Estate — CA DRE# 01265685
Stephanie has been helping Orange County homeowners sell smarter for over 34 years. Fixed Rate Real Estate offers full-service listing representation at a 1% fee — no compromises on service.